Form 843 for Nonprofits: How to Request a Tax Refund or Penalty Abatement
Estimated reading time: 12 minute(s)
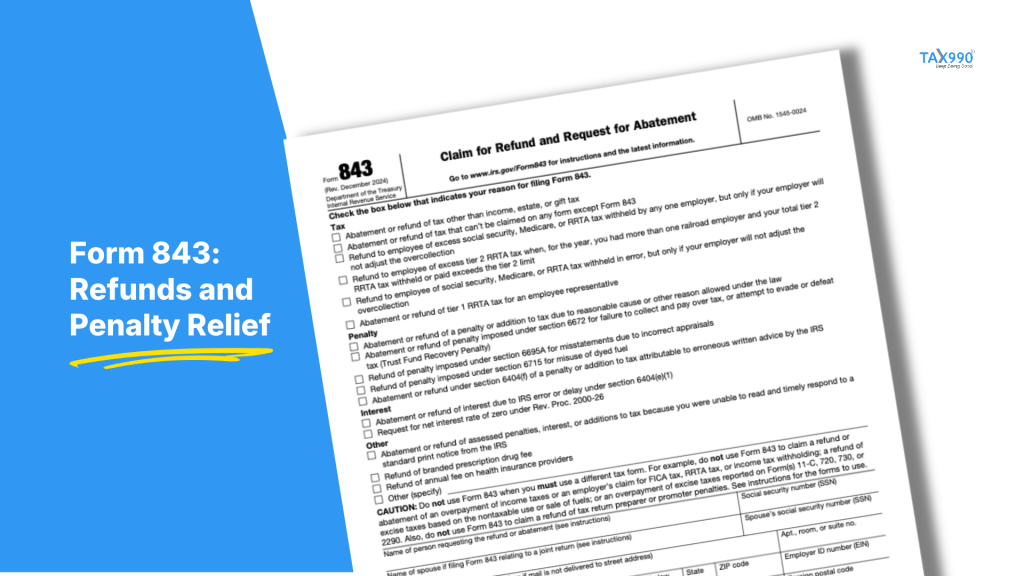
Most nonprofits know Form 990 by heart, but very few have heard of Form 843. That changes the moment your organization is hit with a penalty, interest charge, or fee that never should have been assessed. Form 843 is the form the IRS built for that situation, and knowing when it applies can save your organization real money. Form 843, Claim for Refund and Request for Abatement, is the form nonprofits use to ask the IRS to refund or remove certain taxes, penalties, interest, or fees assessed in error. It applies to items that don’t have a dedicated correction form of their own. Instead of writing a letter and hoping someone reads it, Form 843 gives the IRS a structured claim: what was assessed, why it was wrong, and what relief you’re asking for. For most nonprofits, it comes up after something has already gone sideways. Maybe you paid a penalty you later learned wasn’t owed, or an employee had too much Social Security tax withheld across two jobs. The organization can file Form 843 itself, usually through an officer with signing authority. An authorized representative acting under a valid Form 2848 power of attorney, a paid preparer, or the organization’s accountant can also file on its behalf. This is where organizations get tripped up. Form 843 can’t be used for income, estate, or gift tax refunds or abatements. It doesn’t cover FICA, RRTA, or income tax withholding refunds claimed by an employer, and it can’t amend a return you already filed.Employment tax corrections use Form 941-X, 943-X, 944-X, or 945-X, depending on the original return. Filing Form 843 for the wrong kind of claim only slows things down.What Is Form 843?
Who Can File It?
What Can’t Form 843 Be Used For?
When Might a Nonprofit Need Form 843?
| Reason | What it covers | Who it usually applies to |
| Excise tax abatement or refund | An incorrectly assessed Chapter 42 excise tax, reported on Form 4720 | Private foundations |
| Excess Social Security, Medicare, or Tier 1 RRTA tax | Too much tax withheld when an employee worked for more than one employer in a year | Any nonprofit employer |
| Penalty abatement for reasonable cause | Relief when the organization used ordinary business care but still fell short | Any nonprofit facing a penalty it can show wasn’t due to negligence |
| Trust Fund Recovery Penalty relief (IRC Section 6672) | Personal liability for unpaid payroll taxes | Officers and other responsible persons |
| Interest abatement (IRC Section 6404(e)(1)) | Interest that built up because of IRS error or delay | Any nonprofit billed interest it didn’t cause |
| Erroneous written IRS advice (IRC Section 6404(f)) | Penalty relief after relying on incorrect written IRS guidance | Any nonprofit penalized after following bad written advice |
Reasonable cause is the category most nonprofits reach for first. It means your organization used ordinary business care and prudence but still couldn’t meet a filing or payment obligation. It’s a factual showing, not a formality, so your explanation needs to lay out specifically what got in the way. Timing decides which one you use. To avoid or reduce a Form 990 late filing penalty when you file, the IRS wants a signed reasonable cause statement attached to the return itself. Our guide to reasonable cause relief for late 990 filing explains how to qualify. Form 843 is the right tool once the penalty has already been assessed and billed, and you’re asking the IRS to reverse it. Form 843 is built around checkboxes, IRC citations, and exact dollar figures, and the explanation section is where claims are won or lost. It’s not the moment to guess.Your free Tax990 account includes a fillable Form 843 with plain-language help next to each line, the documents to attach, and where to send it. Form 843 can’t be e-filed, so once it’s complete you download, print, sign, and mail it. Form 843 or a Reasonable Cause Statement?
Fill Out Form 843 With Guidance on Every Line
Generally, you must file within three years from the date you filed the original return or two years from the date you paid the tax, whichever is later. Form 843 won’t show up on your routine filing calendar. But when the situation calls for it, it can mean getting back a penalty your nonprofit didn’t owe. Know what it covers, know what it doesn’t, and act before the filing window closes.And to avoid the next penalty, Tax990 includes extension filing (Form 8868) and deadline reminders when you e-file your Form 990.How Long Do You Have to File?
Final Thoughts
Leave a Comment